

-
Products
- Local Securities
- China Connect
- Grade Based Margin
- Stock Borrowing & Lending
- IPO
- Stock Options
- Foreign Stocks
- Unit Trust
- Local Futures
- Foreign Futures
- Forex
- Bullion
- Insurance Services
- Bond
- Monthly Investment Plan
- Mortgage
- Other Services
- Surplus Cash Facility
- Phillip Premier
- Latest Insurance Promotion<
- Smart Minor (Joint) Account
- ETF
- Capital Management
- Research
- Market Info
- Education Center
- Phillip Apps
Louis Wong Commentary
Author
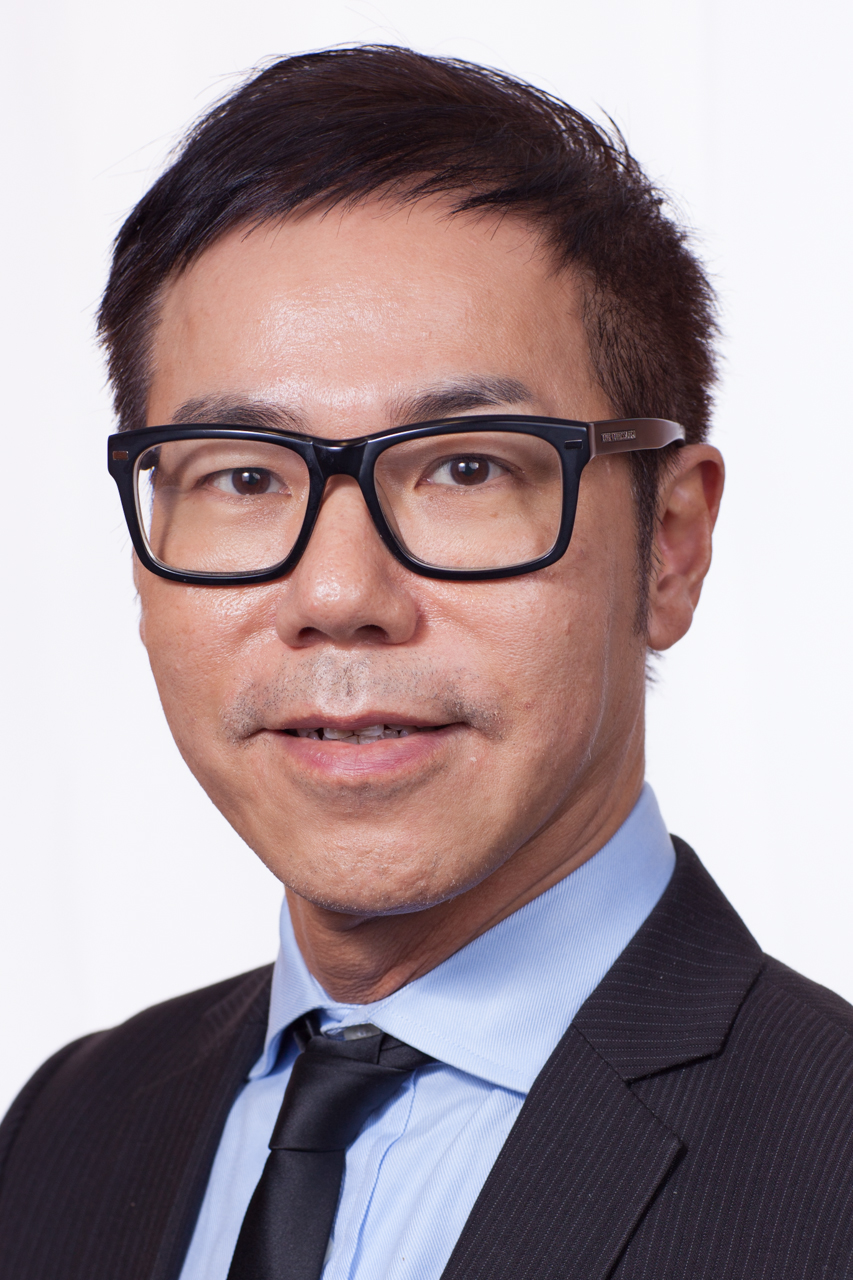
黃瑋傑先生(Louis Wong)
輝立証券董事
見證過去三十多年香港股市每一個牛市和熊市,可謂實戰經驗豐富。現為香港多份財經報章雜誌專欄作家,並為電視台及電台擔任客席主持。個人著作有〈炒得精叻〉、〈投資先知〉及〈股市是平的〉,並獲『中金在線』選為『2010年最受歡迎的港股分析師』。
Phone:
2277 6666
Email:
research@phillip.com.hk
輝立証券董事
見證過去三十多年香港股市每一個牛市和熊市,可謂實戰經驗豐富。現為香港多份財經報章雜誌專欄作家,並為電視台及電台擔任客席主持。個人著作有〈炒得精叻〉、〈投資先知〉及〈股市是平的〉,並獲『中金在線』選為『2010年最受歡迎的港股分析師』。
Phone:
2277 6666
Email:
research@phillip.com.hk
企穩先要重越24000 及補回下跌裂口
Monday, October 5, 2026  223
223
上周港股只有四個交易日,周初恆指仍在24,500點附近拉鋸,踏入10月首個交易日卻大幅下挫,失守24000點,最低見到23865點,收報23,972點,全周下跌538點、跌幅2.2%,連跌四周。國企指數收8,030點,全周跌135點或1.7%,同樣連跌四周;恆生科技指數收4,157點,全周跌153點或3.6%。拖累來自環球債市拋售,英國30年債息一度升至6厘,是1998年以來首次;美國30年債息周內高見約5.69厘,10年期一度觸及5.33厘,同為2002年以來高位。
滬深股市上周只有三個交易日,10月1日起進入國慶休市,要到10月8日才重新開市。上證指數全周跌約1.2%,深成指跌約3.2%。政策上,國慶節前最具體的舉措是住房貸款貼息,10月1日起實施,暫定一年,資金規模不設上限,這解釋了內房和內銀股在成長股回調時能逆勢走強。貨幣政策方面,央行三季度例會刪去「跨周期」表述、更強調逆周期調節,並下調抵押補充貸款(PSL)利率0.25個百分點,更好激勵政策性銀行支持實體經濟、服務國家戰略,並加強對「六張網」建設的金融支持。經濟數據方面,9月官方製造業和非採購經理採購經理指數(PMI)紛紛升回擴張區間。其中,製造業PMI為50.1,符合市場預期,比8月上升0.3個百分點。非製造業商務活動指數為50.2,高於市場預期的49.2,比8月上升1.2個百分點。另外,經季節性調整的RatingDog中國通用製造業採購經理人指數(PMI)在9月錄得52.1,高於市場預期的51.7,並且連續第十個月保持在50榮枯線之上。整體來看,第三季末製造業擴張步伐繼續加快。歷史上國慶前一周偏弱、節後第一周上漲概率較高,統計2011年至2025年(剔除2024年)節後首周全A上漲概率約79%、平均漲幅為1.7%,但第二周又轉弱。
美股方面,美國9月非農新增僅2.9萬人,遠低於市場預期的9萬,8月新增職位向下修訂至增加133,000個,7月職位則修訂為減少10,000個,合共淨減少60,000個職位。9月失業率由8月的4.1%升至4.2%,市場原預期維持不變。10月再加息的概率由一周前的64%急降至22%。不過,債息高居不下,對股市帶來一定壓力,道指與標普按周分別累跌 1.3%與 0.3%,但納指逆勢上揚 0.5%,連續第 3 周上升。
本周關注點有聯儲會議紀要及多位官員講話將透露加息路徑。經濟數據日程上,本周一有9月標普全球服務業PMI終值及ISM非製造業PMI;周二有8月國際貿易數據及三年期國債標售;周四有初請失業救濟金。本周業績較為稀疏,周中稍後才有星座品牌、李維斯等公司。真正决定股市方向的仍是利率:若服務業通脹和油價不再升温,上周五的“加息概率回落”可以延續,標普有條件試前高。反之若ISM物價分項偏熱、或中東局勢再推高油價,長端收益率回到5.3%上方,將壓過就業放緩的利好。
說回港股,A股復市前,成交料繼續偏淡,外圍債息和美股隔夜走勢的影響力會更大。技術上,23,800點是近端支持(10月2日低位已到23,865點),失守則下看23,500點;上方先要重越24,000點,以及補回上周五介於24332點和24099點之間的下跌裂口,較有意義的阻力在24,500至24,600點,亦即10天線一帶。
This report is produced and is being distributed in Hong Kong by Phillip Securities Group with the Securities and Futures Commission (“SFC”) licence under Phillip Securities (HK) LTD and/ or Phillip Commodities (HK) LTD (“Phillip”). Information contained herein is based on sources that Phillip believed to be accurate. Phillip does not bear responsibility for any loss occasioned by reliance placed upon the contents hereof. The information is for informative purposes only and is not intended to or create/induce the creation of any binding legal relations. The information provided do not constitute investment advice, solicitation, purchase or sell any investment product(s). Investments are subject to investment risks including possible loss of the principal amount invested. You should refer to your Financial Advisor for investment advice based on your investment experience, financial situation, any of your particular needs and risk preference. For details of different product's risks, please visit the Risk Disclosures Statement on http://www.phillip.com.hk. Phillip (or employees) may have positions/ interests in relevant investment products. Phillip (or one of its affiliates) may from time to time provide services for, or solicit services or other business from, any company mentioned in this report. The above information is owned by Phillip and protected by copyright and intellectual property Laws. It may not be reproduced, distributed or published for any purpose without prior written consent from Phillip.
Top of Page
|
Please contact your account executive or call us now. Research Department Tel : (852) 2277 6846 Fax : (852) 2277 6565 Email : businessenquiry@phillip.com.hk Enquiry & Support Branches The Complaint Procedures |
About Us Phillip Securities Group Join Us Phillip Network Phillip Post Phillip Channel Latest Promotion 新闻稿 |
E-Check Login |

|
Contact Us
About Us
Phillip Securities Group
Join Us
Phillip Network
Phillip Post
Phillip Channel
Latest Promotion
新闻稿
Phillip Securities Group
Join Us
Phillip Network
Phillip Post
Phillip Channel
Latest Promotion
新闻稿
E-Check
Login